Legal Update
Jun 1, 2020
Main Street Lending Program Update: Federal Reserve Bank of Boston Releases Form Agreements, Instructions, and Updated FAQs in Advance of Program Launch
Sign Up for our COVID-19 Mailing List.
Visit our Beyond COVID-19 Resource Center.
On May 27, 2020, the Federal Reserve Bank of Boston issued a trove of additional details, instructions and documentation for borrowers and lenders regarding the Federal Reserve Board’s (the “Fed”) Main Street Lending Program (the “Main Street Program”), including an updated Frequently Asked Questions document (the “Main Street FAQs”), form borrower and lender certifications, a form loan participation agreement and other form agreements and legal documents (collectively, the “May 27 Guidance”) to be used to implement the Main Street Program in accordance with the Main Street Program term sheets released by the Fed on April 30, 2020. The Main Street Program, the terms of which were originally announced by the Fed on April 9, 2020, and updated on April 30, 2020, was established to purchase up to $600 billion in loans from eligible lenders using funds appropriated to the Fed under the Coronavirus Aid, Relief, and Economic Security Act (“CARES Act”) to support lending to small and medium-sized businesses impacted by the coronavirus disease 2019 (“COVID-19”) pandemic.
This Legal Update summarizes the details of (and key recent revisions to) the Main Street Program based on Fed instruction through the May 27 Guidance.
Borrower Eligibility
As previously announced, businesses created or organized in the US or under US laws prior to March 13, 2020 that were in good financial standing before the COVID-19 crisis are eligible to obtain a Main Street loan if (together with their affiliates) they have either (i) no more than 15,000 employees or (ii) 2019 annual revenues of less than $5 billion. In calculating the number of employees, borrowers must count their and their applicable affiliates’ full-time, part-time, seasonal and other employees and are to exclude volunteers and independent contractors. As specified in the Main Street FAQs, borrowers are to use the average of the total persons employed for each pay period over the 12 months prior to the origination of the Main Street loan. 2019 annual revenues can be calculated either using the borrower’s and its applicable affiliates’ annual “revenues” per 2019 GAAP audited financials or the borrower’s and its applicable affiliates’ receipts[1] for fiscal year 2019 as reported to the Internal Revenue Service. If the borrower (or its affiliate) does not have audited financial statements or annual receipts for 2019, the borrower should use the most recent audited financial statements or annual receipts available.
Eligible borrowers also must have significant operations, and a majority of employees based, in the US. The May 27 Guidance specifies that in order to determine if an eligible borrower has “significant operations” and a “majority of employees” in the US, the business’s operations should be evaluated on a consolidated basis together with its subsidiaries, but not its parent companies or sister affiliates. For example, an eligible borrower has significant operations in the US if, when consolidated with its subsidiaries, greater than 50% of the eligible borrower’s assets are located in the US; annual net income is generated in the US; annual net operating revenues are generated in the US; or annual consolidated operating expenses (excluding interest expense and any other expenses associated with debt service) are generated in the US. The May 27 Guidance notes that the foregoing is a non-exhaustive list of examples that reflects the principles that should be applied by a potential borrower when evaluating its eligibility under this criterion.
As noted in the May 27 Guidance, an eligible borrower may be a US subsidiary of a foreign company that has, on a consolidated basis, significant operations, and a majority of its employees based, in the US. However, a borrower that is a subsidiary of a foreign company must use the proceeds of a Main Street Loan only for the benefit of itself, its consolidated US subsidiaries, and other affiliates of the borrower that are US businesses. The proceeds of a Main Street Loan may not be used for the benefit of an eligible borrower’s foreign parents, affiliates or subsidiaries.
Borrowers also must not be an Ineligible Business listed in 13 CFR 120.110 (b)-(j), (m)-(s), as modified and clarified on or before April 24, 2020 by Small Business Administration (“SBA”) regulations for purposes of the Paycheck Protection Program, created under Title I of the CARES Act to provide aid to small businesses (“PPP”). Such Ineligible Businesses include, among others, hedge funds, private equity funds,[2] banks, life insurance companies, passive real estate investment companies and most government-owned entities. Businesses, such as airline carriers, that received support pursuant to Section 4003(b)(1)-(3) of the CARES Act, likewise are ineligible to participate in the Main Street Program.
In addition, companies that have taken advantage of the PPP may obtain both a PPP loan and a Main Street loan. However, businesses (and their affiliated companies) will only be eligible under the Main Street Program to obtain one of the Main Street loans and must not also participate in the Fed’s Primary Market Corporate Credit Facility (PMCCF), which will purchase corporate bonds from eligible issuers. In the May 27 Guidance, the Fed provided additional details around this restriction, as well as supplemental information regarding the previously announced applicability of the SBA affiliation rules.[3] Specifically:
- If any affiliate of the business has participated in the PMCCF, the business may not borrow under the Main Street Program.
- If an affiliate has previously participated, or has a pending application to participate, in the Main Street Program, the business can only participate in the Main Street Program by choosing the same Main Street loan accessed by its affiliate. For example, if an eligible borrower’s affiliate has a New Loan, then the borrower would only be able to obtain a New Loan and would be prohibited from obtaining a Priority Loan or an Expanded Loan.
- In no case may the affiliated group’s total participation in a single Main Street facility exceed the maximum loan size that the affiliated group is eligible to receive on a consolidated basis. As a result, an eligible borrower’s maximum loan size would be limited by its own leverage level, the leverage level of the affiliated group on a consolidated basis, and the size of any loan extended to other affiliates in the group. For example, in the case of a New Loan, the eligible borrower’s maximum loan size would be the lesser of:
- $25 million (less any amount extended to an affiliate of the eligible borrower under the New Loan);
- an amount that, when added to the eligible borrower’s existing outstanding and undrawn available debt, does not exceed four times the eligible borrower’s adjusted 2019 earnings before interest, taxes, depreciation and amortization (“EBITDA”); or
- an amount that, when added to the eligible borrower’s affiliated group’s existing outstanding and undrawn available debt, does not exceed four times the affiliated group’s adjusted 2019 EBITDA.
The Main Street Program is designed to be accessible to much larger businesses, and while SBA affiliation rules will apply to Main Street loans as noted above, a number of businesses (including, in some cases, private equity- and venture capital-owned firms) that were ineligible for PPP loans should be able to participate in the Main Street Program, provided they satisfy other eligibility requirements. Additionally, much of the real estate industry should be able to participate in the Main Street Program.
Non-profit entities continue to be ineligible for Main Street loans. The Fed, however, has acknowledged the unique needs of non-profit organizations and has indicated that the Fed and the Treasury Department will be evaluating the feasibility of adjusting the borrower eligibility criteria and loan eligibility metrics of the Main Street Program for non-profit entities.
Key Terms
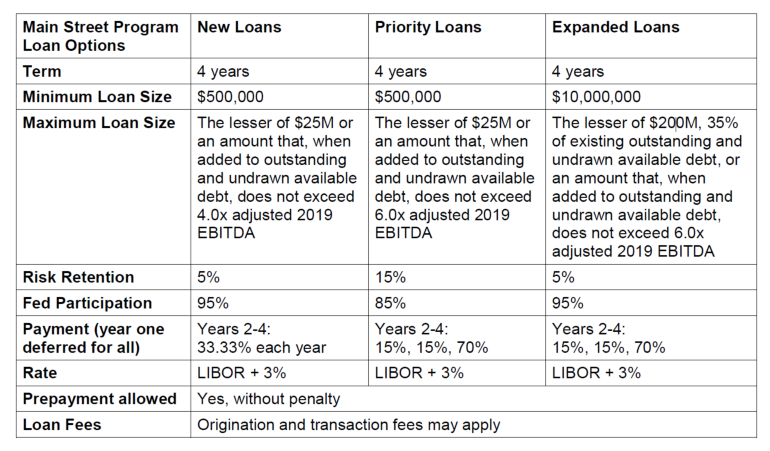
As previously announced, the Main Street Program includes three types of loans, which share a number of features, including the eligibility criteria for borrowers and lenders, maturity, interest rate, deferral of principal and interest for one year, and ability of the borrower to prepay without penalty, but have other differences, including with respect to the level of pre-crisis indebtedness an eligible borrower may have incurred. The following key terms of the loans remain as originally publicized on April 30, 2020.
New Loans
Loan sizes for new Main Street loans (i.e., those originated on or after April 24, 2020) (“New Loans”) will range from a minimum principal amount of $500,000 up to a maximum principal amount that is the lesser of (i) $25 million or (ii) an amount that, when added to the borrower’s existing outstanding and undrawn available debt, is less than or equal to four times the borrower’s 2019 adjusted EBITDA. The term of New Loans will be 4 years, with principal amortization of one-third at the end of the second, third and fourth year. New Loans may not be, at the time of origination and during the term of the loan, junior in priority in bankruptcy[4] to the borrower’s other unsecured loans or debt instruments.
Priority Loans
Loan sizes for new Main Street priority loans (i.e., those originated on or after April 24, 2020) (“Priority Loans”) will range from a minimum principal amount of $500,000 up to a maximum principal amount that is the lesser of (i) $25 million or (ii) an amount that, when added to the borrower’s existing outstanding and undrawn available debt, is less than or equal to six times the borrower’s adjusted 2019 EBITDA. The term of Priority Loans will be 4 years, with principal amortization of 15% at the end of the second and third year, and a balloon payment of 70% at the end of the fourth year. At the time of origination and at all times while the loan is outstanding, a Priority Loan must be senior to or pari passu with, in terms of priority and security,[5] the borrower’s other loans or debt instruments, other than mortgage debt.
The borrower may, at the time of origination of a Priority Loan, refinance existing debt owed by the borrower to a lender that is not the eligible lender under the Main Street Program. After origination and until the Priority Loan is repaid in full, however, the borrower must refrain from repaying the principal balance of, or paying any interest on, any debt other than the Priority Loan, unless the debt or interest payment is mandatory and due, as described in more detail below.
Expanded Loans
The maximum size for the upsized tranche of any existing loans (i.e., those originated before April 24, 2020) (the upsized tranche of such loans, “Expanded Loans”) will range from a minimum principal amount of $10 million up to a maximum principal amount that is the lesser of (i) $200 million, (ii) 35% of the borrower’s existing outstanding and undrawn available debt that is pari passu in priority with the loan and equivalent in secured status (i.e., secured or unsecured)[6] or (iii) an amount that, when added to the borrower’s existing outstanding and undrawn available debt, is less than or equal to six times the borrower’s adjusted 2019 EBITDA.
To be eligible for “upsizing,” the existing term loan or revolving credit facility must have been originated on or before April 24, 2020, and must have a remaining maturity of at least 18 months. The lender may extend the maturity of an existing loan or revolving credit facility at the time of upsizing in order for the underlying instrument to satisfy the 18-month remaining maturity requirement. At the time of upsizing and at all times thereafter, the Expanded Loan must be senior to or pari passu with, in terms of priority and security, the borrower’s other loans or debt instruments, other than mortgage debt.[7] The term of the Expanded Loan will be 4 years, with principal amortization of 15% at the end of the second and third year, and a balloon payment of 70% at the end of the fourth year.
As noted in the May 27 guidance, the lender of the Expanded Loan is not required to have been the lender that originally extended the loan underlying an Expanded Loan. However, the lender must have purchased the interest in the underlying loan as of December 31, 2019, and the lender must have assigned an internal risk rating to the underlying loan equivalent to a “pass” in the FFIEC’s supervisory rating system as of that date.
If the existing term loan is a multi-lender facility that does not have an “opening” or “accordion” clause, it can still be eligible for upsizing as an Expanded Loan if the borrower, eligible lender(s) and any other required parties amend the underlying credit agreements to comply with the requirements set out in the Expanded Loan term sheet.
Per the May 27 Guidance, the lender cannot share its 5 percent retention of an Expanded Loan with other members of a multi-lender facility and must retain 5% of the Expanded Loan.
The Fed has explained that Expanded Loans have a minimum loan size of $10 million rather than the $500,000 minimum of New Loans and Priority Loans, because Expanded Loans were designed to meet the needs of borrowers with existing loan arrangements, particularly those with larger and more complex existing loans, where pre-existing loan documentation can be used.
Other Terms
All Main Street loans are term loans (no revolving loans are available at this time), may be prepaid without penalty and will be subject to an adjustable interest rate of 1- or 3- month LIBOR + 3%. The May 27 Guidance expressly prohibits the application of any other interest rate. Amortization on Main Street loans will be deferred for one year and no payments of principal or interest will be due during this period. Unpaid interest will be capitalized.
New Loans and Priority Loans may be secured or unsecured. An Expanded Loan must be secured if the underlying loan is secured. In such case, any collateral securing the underlying loan (at the time of upsizing or on any subsequent date) must secure the Expanded Loan on a pari passu[8] basis, and, if the borrower defaults, the Main Street Program and lender(s) would share equally in any collateral available to support the loan relative to their proportional interests in the loan. The lenders can require borrowers to pledge additional collateral to secure an Expanded Loan as a condition of approval.
In the May 27 Guidance, the Fed clarified that, for New Loans and Priority Loans, the methodology the lender requires an eligible borrower to use when calculating the borrower’s adjusted 2019 EBITDA must be a methodology such lender previously required to be used for adjusting EBITDA when extending credit to the applicable borrower or similarly situated borrowers (i.e., borrowers in similar industries with comparable risk and size characteristics) on or before April 24, 2020. For Expanded Loans, the methodology a lender requires an eligible borrower to use when calculating the borrower’s adjusted 2019 EBITDA must be the methodology the lender previously required to be used for adjusting EBITDA when originating or amending the underlying loan on or before April 24, 2020. If a lender has used a range of EBITDA adjustment methods in the past, the lender should choose the most conservative method and, in any event, must select a single method used in the recent past before April 24, 2020. The lender may not “cherry pick” or apply adjustments used at different points in time or for a range of purposes. Additionally, the lender should document the rationale for its selection of an adjusted EBITDA methodology and should likewise document its process for identifying “similarly situated borrowers”.
Additionally, if a borrower’s existing debt arrangements require prepayment of an amount that is not de minimis upon the incurrence of new debt, the borrower cannot receive a New Loan or an Expanded Loan unless such requirement is waived or reduced to a de minimis amount by the relevant creditor.
Unlike the popular PPP program, Main Street loans will not be eligible for loan forgiveness. However, as noted in the May 27 Guidance, in the event of restructurings or workouts, the Fed may agree to reductions in interest (including capitalized interest), extended amortization schedules and maturities, and higher priority “priming” loans.
Borrowers of New Loans and Priority Loans will pay an origination fee to the lender of 1% of the principal amount of the applicable loan. Borrowers of the Expanded Loans will pay an “upsizing” fee to the lender of 0.75% of the principal amount of the Expanded Loan. Additionally, the lenders will be required to pay the Main Street Program a transaction fee of 1% of the principal amount of any New Loan or Priority Loan, or 0.75% of the principal amount of the Expanded Loan, at the time of origination or upsizing, as applicable, and may elect to pass this fee on to the borrower. The May 27 Guidance instructs that lenders are not permitted to charge borrowers any additional fees, except de minimis fees for services that are customary and necessary in the lender’s underwriting of commercial and industrial loans to similar borrowers, such as appraisal and legal fees. Lenders should not charge servicing fees to borrowers.
The Main Street Program will cease participations on September 30, 2020 unless extended by the Treasury Department and the Fed.
Certifications and Covenants
Various borrower and lender certifications and covenants will be required in connection with each Main Street loan. The May 27 Guidance includes several standalone documents containing detailed instructions and guidance for borrower and lender certifications and covenants.
Borrower Certifications and Covenants
Borrowers must provide the required certifications and covenants in a writing executed on behalf of the borrower by its principal executive officer and principal financial officer or functional equivalents.
As noted, the May 27 Guidance provides additional details for the borrower to take into account in determining whether the previously announced certifications (identified below) can be made.
1. The borrower will not use the proceeds of the loan to repay principal or interest on any other debt (other than mandatory principal or interest payments that are due, or, in the case of Priority Loans, debt owed to a lender other than the Priority Loan lender refinanced at the time of the origination of the loan) until the Main Street loan is fully repaid.
Per the May 27 Guidance, under the Main Street Program, borrowers may continue to pay, and lenders may request that borrowers pay, interest or principal payments on outstanding debt on (or after) the payment due date, provided that the payment due date was scheduled prior to April 24, 2020. Borrowers may not pay, and lenders may not request that borrowers pay, interest or principal payments on such debt ahead of schedule during the life of the Main Street loan, unless required by a mandatory prepayment clause as specifically permitted above. For future debt incurred by the borrower in compliance with the terms and conditions of the Main Street loan, principal and interest payments are “mandatory and due” on their scheduled dates or upon the occurrence of an event that automatically triggers mandatory prepayments.
2. The borrower will not seek to cancel or reduce any of its committed lines of credit.[9]
3. The borrower is unable to secure adequate credit accommodations from other banking institutions.
Per the May 27 Guidance, being unable to secure adequate credit accommodations does not mean that no credit from other sources is available to the borrower. Rather, the borrower may certify that it is unable to secure “adequate credit accommodations” because the amount, price, or terms of credit available from other sources are inadequate for the borrower’s needs during the current unusual and exigent circumstances. Borrowers are not required to demonstrate that applications for credit had been denied by other lenders or otherwise document that the amount, price, or terms of credit available elsewhere are inadequate.
4. The borrower has a reasonable basis to believe that, as of the date of origination or upsizing, as applicable, and after giving effect to such loan, it has the ability to meet its financial obligations for at least the next 90 days and does not expect to file for bankruptcy during that time period.
5. The borrower is not Insolvent as that term is used in 12 CFR 201.4(d)(5)(iii).
Per the May 27 Guidance, a borrower would not be Insolvent or generally failing to pay its undisputed debts as they become due because of reduced business activity resulting from stay-at-home, shelter-in-place, social distancing, or other similar orders or recommendations by government authorities related to the COVID-19 pandemic, or if expected and routine sources of funding were unexpectedly unavailable because of market conditions resulting from the COVID-19 pandemic. However, a person or entity failing to pay undisputed debts as they become due for reasons unrelated to COVID-19 would be Insolvent.
6. The borrower (i) has provided financial records to the lender and a calculation of the borrower’s (and affiliates’) adjusted 2019 EBITDA, reflecting only permitted adjustments and (ii) such financial records fairly present, in all material respects, the financial condition of such entities for the period covered thereby in accordance with GAAP, consistently applied, and such calculations are true and correct in all material respects.
7. The borrower must make certifications as to its other debt amounts and with respect to its other debt obligations’ compliance with the Main Street Program requirements concerning priority and security, as described in more detail in the form of borrower certifications and covenants included in the May 27 Guidance.
8. The borrower will follow compensation, stock repurchase, and capital distribution restrictions that apply to direct loan programs under section 4003(c)(3)(A)(ii) of the CARES Act (with certain modifications introduced by the Fed, including that an S corporation or other tax pass-through entity that is a borrower may make distributions in respect of its common stock equivalents to the extent reasonably required to cover its owners’ tax obligations in respect of the entity’s earnings), i.e.
a. Compensation restrictions:
i. For officers and employees whose total compensation exceeded $425,000 (but was less than $3 million) in 2019 or, if applicable, a subsequent reference period (as described below), borrowers may not, beginning the year of the loan and continuing for the one-year period following the satisfaction of the loan, pay such officer or employee during any 12 consecutive month period more compensation than that officer or employee received in 2019 or the subsequent reference period or pay severance/other benefits upon termination of employment with the borrower that exceed twice the maximum total compensation in 2019 or the subsequent reference period. The May 27 Guidance specifies that these restrictions do not apply to any employee whose compensation is determined through an existing collective bargaining agreement entered into prior to March 1, 2020.
ii. For officers and employees whose total compensation exceeded $3 million in 2019 or the subsequent reference period, borrowers may not, beginning the year of any loan and continuing for the one-year period following the satisfaction of the loan, pay such officer or employee during any consecutive 12 month period more than $3 million plus 50% of the amount over $3 million received by the officer in 2019 or the subsequent reference period or, except for an employee whose compensation is determined through an existing collective bargaining agreement entered into prior to March 1, 2020, pay severance pay/other benefits upon termination of employment with the borrower that exceed twice the maximum total compensation in 2019 or the subsequent reference period.
The May 27 Guidance introduces restrictions applicable to new hires and existing officers or employees who become highly compensated. Specifically, for an officer or employee whose employment with a borrower started during 2019 or later, the “subsequent reference period” is the 12-month period starting from the end of the month in which the individual began employment, if his or her total compensation exceeds $425,000 during such period. For an officer or employee whose total compensation first exceeds $425,000 during a 12-month period ending after 2019, the “subsequent reference period” is the 12-month period starting from the end of the month in which his or her total compensation first exceeded $425,000.
The May 27 Guidance also instructs that “officers or employees” mean individuals who perform compensated services for a borrower and either (a) for whom, in connection with those services, the borrower would be responsible for reporting the compensation on Form W-2 and withholding federal income taxes (regardless of whether the compensation is subject to withholding or tax is withheld) or (b) is a partner in a partnership, member of a limited liability company or similar. Independent contractors and independent directors are not considered officers or employees.
“Total compensation” includes salary, bonuses, awards of stock and other financial benefits provided by the borrower and its affiliates to an officer or employee of the borrower.
b. Stock repurchase/capital distributions prohibitions: Borrowers with direct loans cannot, absent a waiver from the Fed, engage in stock buybacks, unless required under pre-existing contracts in effect as of March 27, 2020, or pay dividends or make other capital distributions with respect to the common stock equivalents of the borrower, until one year after the date the Main Street loan is no longer outstanding, subject to the exception with respect to S-corporations or other pass-through entities.
Consistent with the CARES Act, the prohibition on stock buybacks is limited to borrowers that have, or have a parent company that has, equity securities listed on a national securities exchange.
The May 27 Guidance also instructs that dividends and other capital distributions means any payment made with respect to the borrower’s common stock equivalents, including discretionary dividend payments, and would include mandatory or preferential payments of dividends or other distributions in respect of preferred stock unless both the equity interest and the obligation to pay dividends or distributions existed as of March 27, 2020. Dividends and other capital distributions do not include repurchases or redemptions. Per the May 27 Guidance, any tax distributions made pursuant to the exception for pass-through entities shall be subject to an annual reconciliation, with any surplus or deficiency to be deducted from or added to distributions, as applicable, in the following year.
9. The borrower will use the proceeds of the loan only for the benefit of the borrower, its consolidated US subsidiaries and other affiliates of the borrower that are US businesses.
10. The borrower is eligible to participate in the Main Street Program, including by meeting all eligibility criteria described above and in light of the conflicts of interest prohibition in section 4019(b) of the CARES Act (“Conflicts of Interest Prohibition”)—i.e., Businesses in which the President, Vice President, an executive department head, Member of Congress—or such individual’s spouse, child (including adult children), son-in-law, or daughter-in-law (each a “covered individual”)—own, control or hold at least a 20% direct or indirect equity stake (by vote or value) of the outstanding amount of any class of equity interest will not be eligible for emergency relief funds under Title IV of the CARES Act, including Main Street Program funds.
As detailed in the May 27 Guidance, for purposes of the Conflicts of Interest Prohibition, a covered individual’s indirect equity interest by value shall be calculated on a proportional basis, taking into account any partial ownership of the relevant entity’s parents. A share is considered an ownership interest without regard to whether it is transferable or classified as stock or anything similar and without regard to whether it is a voting security. Warrants, options and similar rights must be counted even if they are unexercised or “out of the money”. The May 27 Guidance provides instructions for the diligence required to determine whether the Conflicts of Interest Prohibition is triggered. Specifically, the borrower is responsible for any “actual knowledge” of the borrower and is required to determine the beneficial owner of any 5 percent or greater equity interest of the entity and whether such beneficial owner is a covered individual by checking the name against a list of government officials provided in the May 27 Guidance and by asking each such beneficial owner whether the owner is a covered individual. To determine the identify of beneficial owners of publicly traded securities, borrowers are entitled to rely on information disclosed in Securities Exchange Act sections 13(d) and 13(g) filings.
The certifications and covenants also include an indemnification by the borrower of the beneficiaries of such certifications and covenants in respect of losses arising out of a material breach of any certifications or covenants.
The requirements that the borrower certify that (i) it requires financing due to the exigent circumstances presented by COVID-19 and (ii) it will make reasonable efforts to maintain its payroll and retain its employees during the term of the loan were deleted in the April 30, 2020 versions of the Main Street Program term sheets and remain absent in the May 27 Guidance. The Fed indicated that each borrower that participates in the Main Street Program should make commercially reasonable efforts to maintain its payroll and retain its employees during the term of the loan. As announced
Seyfarth Shaw LLP provides this information as a service to clients and other friends for educational purposes only. It should not be construed or relied on as legal advice or to create a lawyer-client relationship. Readers should not act upon this information without seeking advice from their professional advisers.